Recurring customers
How much of last year’s revenue came from customers who also bought the year before, and the year before that? Long-standing accounts with steady reorders are worth more than one-off project sales.
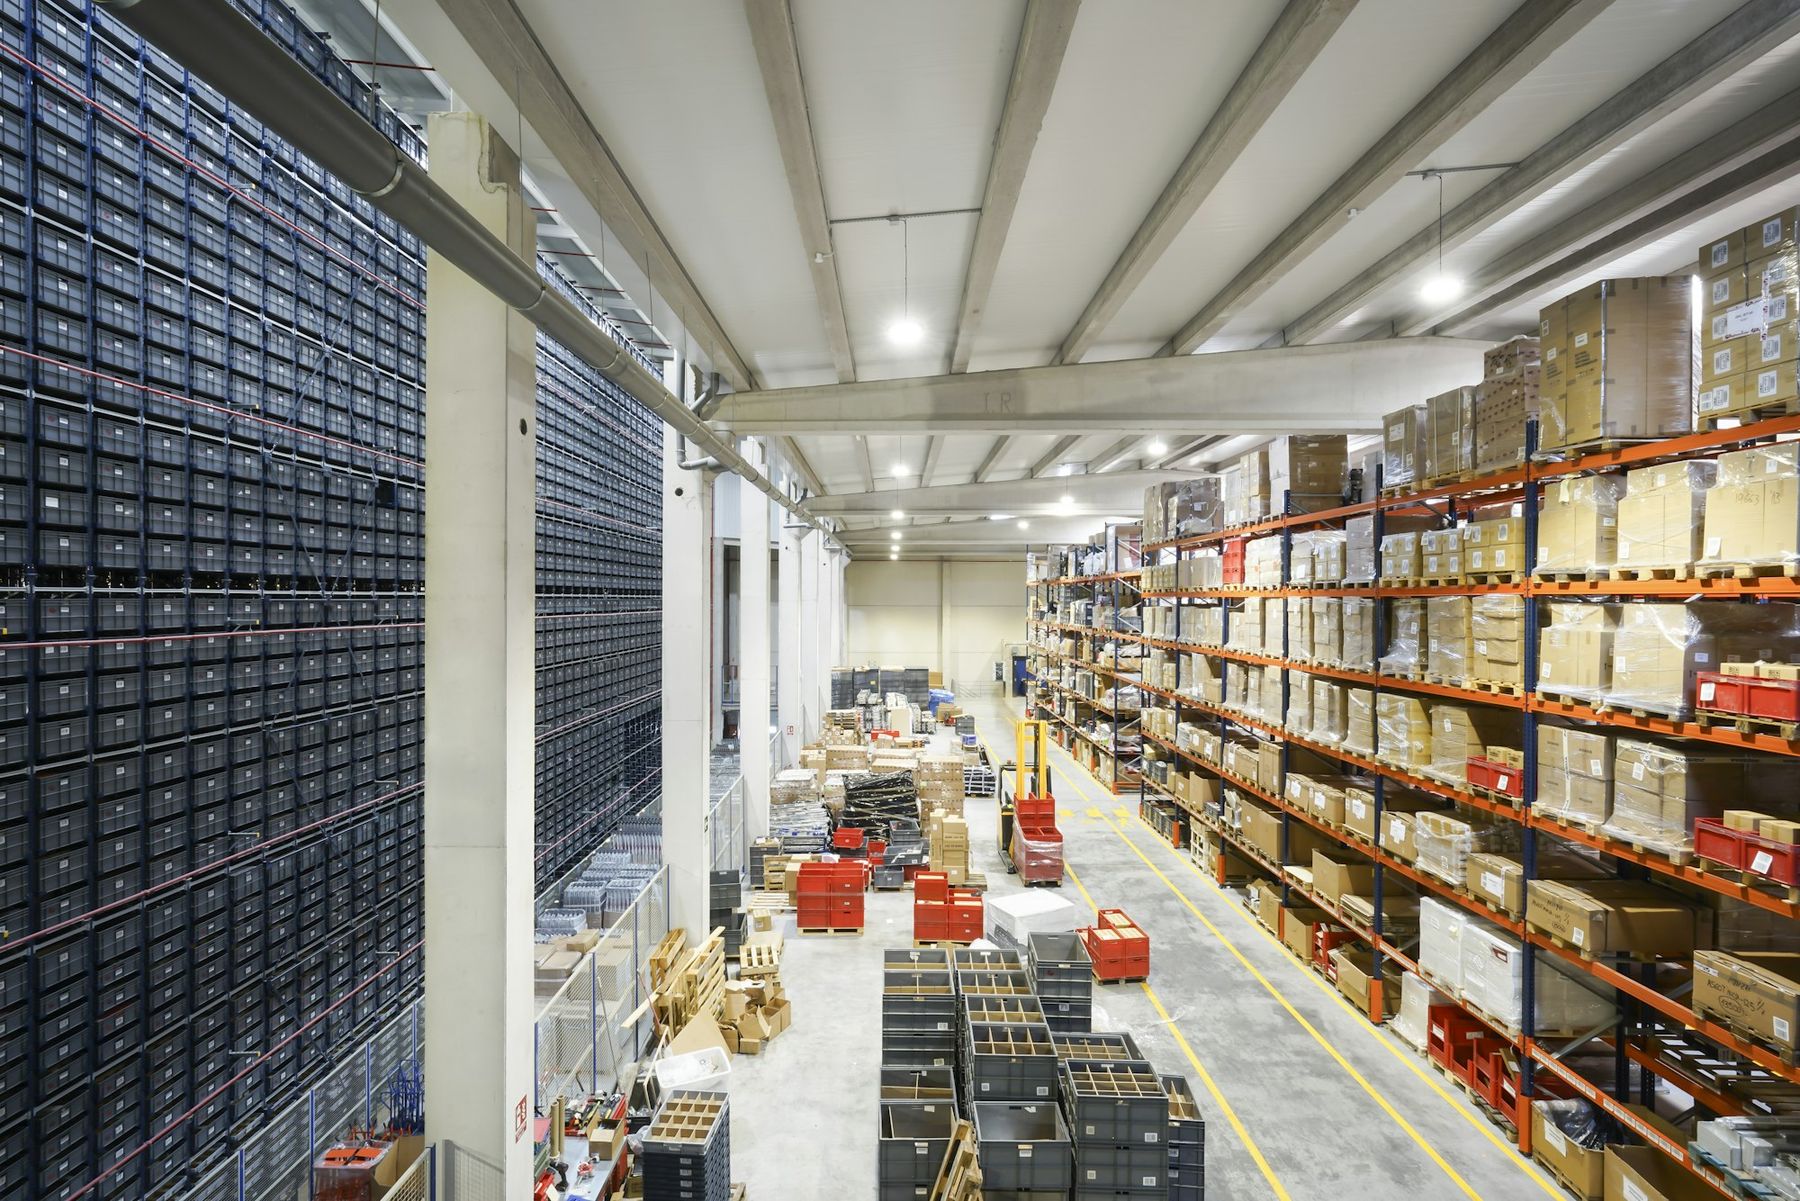
Industrial, building-materials, equipment and consumer-goods distributors, importers and supply companies. Buyers want to know whether your supplier lines, customers and margins will hold after you leave, and what is really in the warehouse. Kingston Investments advises owners of privately held distribution and wholesale businesses on valuation, buyer identification, negotiations and the sale process, across Ontario from the Greater Toronto Area.
A distributor is valued on the earnings it produces from its supplier lines and customer relationships, and on how confident a buyer can be that both will transfer. Inventory and working capital then decide how much of the price you actually take home.
Buyers want to know why your gross margin is what it is, and whether it holds when prices, product mix or supplier rebates change.
Exclusive or important lines that a supplier could end after a sale are the first thing a buyer will test.
Slow-moving and obsolete stock is usually discounted or excluded, and the working capital target can move the final price.
Recurring customers, diversified suppliers and clean inventory records make a business more attractive to certain buyers. Their absence doesn’t make it unsaleable, but it shapes the price and terms.
Two distributors with the same sales can be worth very different amounts. The difference is usually in the gross margin and how dependable it is.
Gross margin is what remains from sales after the cost of the products you sell. For a distributor, it pays for the warehouse, the trucks, the sales team and everything else. A buyer will want to see it month by month, by product line and by major customer, and will try to separate the effects of price increases, volume growth, product mix and supplier rebates.
Margins earned through value-added services, such as technical support, kitting, repairs, fast delivery or inventory held on behalf of customers, tend to be stickier than margins that rely only on price. Margins that depend on a single rebate program or one unusually profitable account are viewed more cautiously.
We rebuild your margin history the way a buyer will, so you know what the figures say before anyone else reads them.
Your supplier agreements are often the most valuable thing a buyer acquires and the easiest to lose. Buyers will read each important agreement for its term, territory, exclusivity and what happens on a change of ownership.
Supplier concentration. If one supplier’s products make up a large share of your sales, the buyer is effectively relying on that supplier’s goodwill. Diversifying lines takes time, which is another reason to start planning early.
For most distributors, inventory and receivables are the largest items on the balance sheet. Two things matter in a sale: what the inventory is really worth, and how much working capital the buyer expects you to leave behind.
Purchase agreements usually set a normal level of working capital, roughly receivables plus inventory minus payables, that must be in the business at closing. The price is then adjusted up or down. If the target is set from an unusual month, or inventory is counted differently from how it was measured, the difference comes out of your proceeds.
Buyers value repeat customers who keep ordering whoever owns the business. These are the questions we prepare owners to answer.
How much of last year’s revenue came from customers who also bought the year before, and the year before that? Long-standing accounts with steady reorders are worth more than one-off project sales.
What happens if the largest customer leaves? Buyers look at the share of gross profit, not just sales, from the top accounts, and at any contracts or pricing agreements behind them.
Outside sales reps, inside sales, counter sales, contractor accounts and online ordering each carry different costs and risks. Buyers want to know which ones are growing and who owns the relationships.
If the owner holds the key supplier and customer relationships personally, buyers worry they leave with the owner. Bringing a sales manager or key account people into those relationships early reduces that concern.
Strategic buyers are often the most interested in distributors, but they aren’t the only ones.
Adding a territory, product line or customer base. They may pay for overlap they can remove, such as warehouses or overhead, but they will also look hard at which lines and customers stay.
Buying their own route to market, or securing the distributor that sells their products. Their interest can depend on how important the business is to their sales.
Building a group of distributors in a sector. They want stable margins, reliable reporting and a management team that stays.
Experienced managers looking to own a business. Usually financed by a bank, so inventory and receivables help support the loan, and seller financing may be part of the deal.
Distributors that can produce these reports quickly look well run, and buyers trust the rest of their numbers more.
What to expect in due diligenceWant to know how a buyer would see your numbers?
Share a few details and an advisor will review them and contact you to talk about value. Confidential, with no obligation.
A distribution sale has more moving parts than most: suppliers, customers, inventory and working capital all need managing. We plan the order in which each one is handled.
Sell-side advisory Our full process, step by stepWe normalize earnings and rebuild margins by line and customer, and review inventory quality and working capital, so the numbers hold up when a buyer tests them.
We review the key agreements and relationships, identify what needs consent or comfort, and agree with you when and how suppliers should be approached.
Strategic and financial buyers see an anonymous profile first and sign a non-disclosure agreement before receiving detail. Competitors receive the most sensitive information last.
We help you compare offers on structure as well as price, including how inventory will be counted and how the working capital target is set.
We coordinate the inventory count, supplier and customer confirmations, and the work of your accountant, lawyer and the buyer’s lender through to closing.
Completed transactions from Kingston’s portfolio. To protect our clients, businesses and parties are not named, and some values are confidential.
Distribution & wholesale
Published value $2,000,000
Sold
View detailsDistribution & wholesale
Deal value Undisclosed
Sold
View detailsDistribution & wholesale
Deal value Undisclosed
Sold
View detailsDistribution & wholesale
Deal value Undisclosed
Sold
View detailsKingston screened out unqualified inquiries and introduced only serious prospective buyers, saving me considerable time while I continued operating the company. Their communication was excellent, and they remained professional and reliable throughout the sale process.
Short answers to the questions we hear most often. Every business is different, so we’re happy to talk through yours.
All FAQsUsually on normalized earnings, adjusted EBITDA for most established distributors or seller’s discretionary earnings for smaller owner-run ones, judged against how dependable those earnings are. Buyers look closely at gross margin stability, supplier agreements, customer retention and concentration, inventory quality and how much working capital the business needs to operate.
It depends on the agreements. Some can be assigned, some need the supplier’s consent, and some can be ended if the company changes hands. Informal relationships carry their own uncertainty. We review the agreements early, and in many sales the buyer will want comfort from key suppliers before closing, so how and when to approach them needs planning.
Buyers typically value inventory they expect to sell in the normal course of business. Slow-moving stock is often discounted or negotiated, and obsolete stock is usually written down or excluded. A recent physical count, an inventory aging report and clear write-down policies make this a short discussion rather than a long one.
Most purchase agreements set a normal level of working capital, mainly receivables plus inventory minus payables, that the business must have at closing. If the actual amount is higher or lower, the price is adjusted. For distributors, where inventory and receivables are large, how that target is set can change what you receive by a meaningful amount.
It can, if it is secure, long enough to matter and transferable to a new owner. An exclusive territory a supplier can end on short notice, or after a change of control, offers less comfort. Buyers will weigh the strength of the agreement, the supplier’s importance to your sales and how easily customers could buy the same products elsewhere.
It varies with the size of the business, how prepared it is and the buyer’s financing. Preparation, marketing, negotiation, due diligence and closing together often take many months, and some sales take a year or more. Supplier discussions and inventory counts can affect timing, so we plan for them from the start.
A business broker typically lists a business and responds to the buyers who come forward, which suits many smaller, simpler sales. An M&A advisor, sometimes called a business sale advisor, prepares the business for a buyer’s scrutiny, normalizes the financial statements, approaches suitable buyers confidentially, negotiates price and terms, and manages due diligence through to closing. Where supplier agreements, inventory and working capital targets drive the outcome, as they do in most distributors, an advisor’s preparation and negotiation usually matter.
No. A conversation two or three years ahead gives you time to diversify suppliers, document customer relationships, clean up inventory and tighten financial reporting, which are often the changes that matter most to buyers.
We normalize the financial statements, analyse margins and working capital the way a buyer will, help you set realistic price expectations, prepare the confidential information package, approach and screen buyers, coordinate supplier and customer questions at the right stage, help you compare offers and manage due diligence through to closing.
Knowing roughly what your business is worth helps with planning long before a sale. Here’s how buyers arrive at a number, and why it comes as a range.
A practical timeline for owners who expect to sell in the next year or two, from getting an honest starting point to the months just before going to market.
Two offers at the same price can leave you in very different places. Here’s how to read the terms around the number before you choose.
Confidential conversation
Start with a confidential conversation about your supplier lines, customers and margins, and what a buyer is likely to see. There’s no obligation.